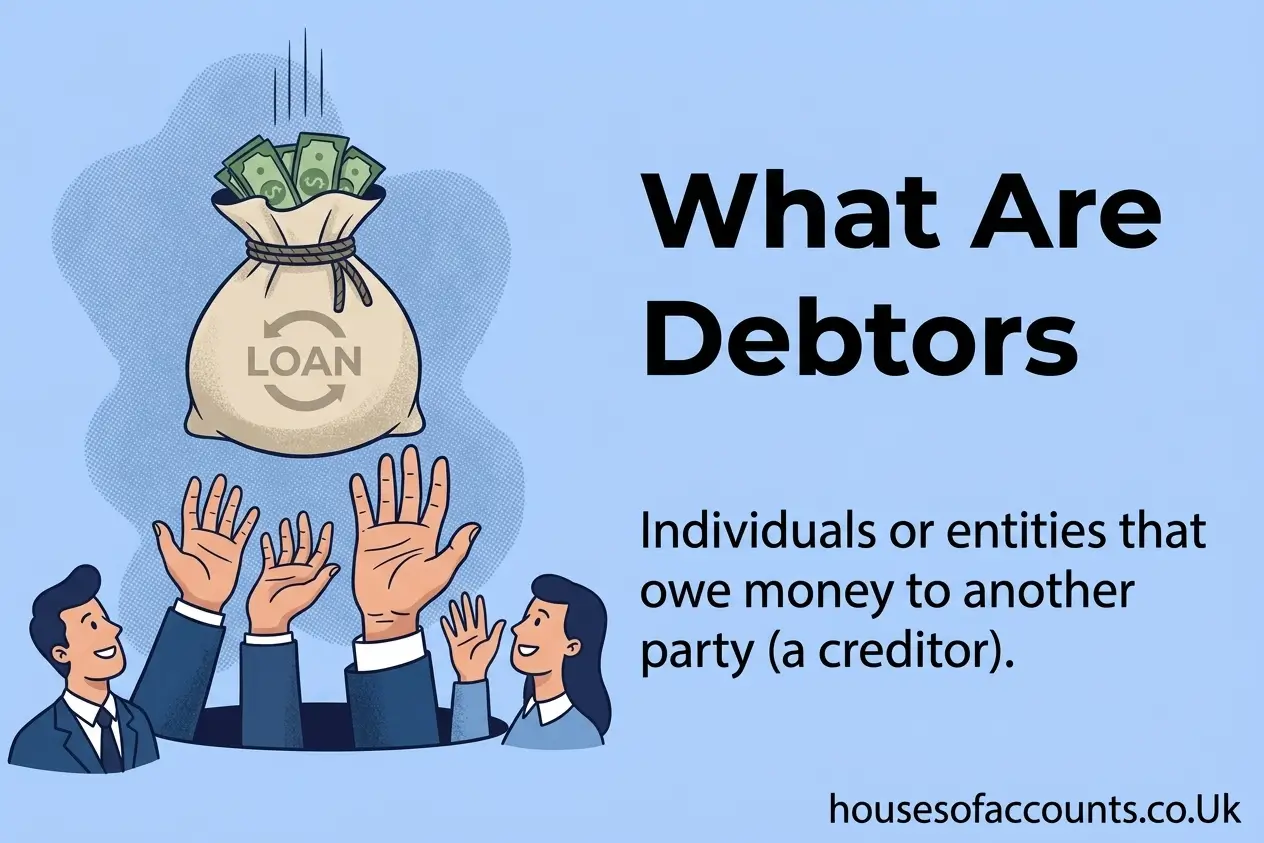
What Are Debtors is a basic accounting question, but the answer has an important connection with how businesses manage sales, invoices, and cash flow. A debtor is a person, customer, or organisation that owes money to a business. The amount usually becomes due because the business has supplied goods or services before receiving payment.
When considering What Are Debtors, it is also important to understand the difference between money owed and money received. An invoice can represent a genuine sale, but the business does not have the cash until the customer makes payment. For this reason, debtor balances need to be monitored carefully as part of normal financial management.
What Does Debtor Mean in Accounting?
In accounting, a debtor is generally someone who has an outstanding financial obligation to the business. For most businesses, debtors are customers who have purchased products or services on credit.
For example, an architecture firm completes professional services worth £6,000 for a commercial client. The firm issues an invoice with payment due within 30 days. Until the client settles the invoice, £6,000 remains outstanding and is recorded as a receivable.
The customer is therefore a debtor of the architecture firm.
The accounting term trade receivables is often used for these customer balances. Although the words debtor and receivable are commonly used interchangeably in business conversations, receivables more specifically describe amounts the business expects to collect.
How Do Debtor Balances Arise?
A debtor balance normally begins when a business agrees to provide goods or services on credit.
The Credit Sales Process
A typical transaction involves several stages:
-
The customer places an order or agrees to a service.
-
The business supplies the goods or completes the work.
-
An invoice is issued.
-
The invoice specifies the amount and payment terms.
-
The amount becomes a receivable in the business records.
-
The customer pays.
-
The payment is recorded and the outstanding balance is reduced.
Consider a commercial cleaning company that provides monthly cleaning services to an office. It invoices the client at the end of the month with 14-day payment terms. During those 14 days, the invoice contributes to the company's debtor balance.
If the client pays on time, the receivable is converted into cash without becoming overdue.
Are All Debtors Overdue?
No. This is one of the most useful distinctions to understand.
A debtor simply owes money. The customer may still be within the agreed payment period.
For instance, an invoice issued on 10 November with payment due on 10 December creates a debtor balance. The customer is not necessarily late during November.
Once 10 December passes without payment, the invoice can be classified as overdue according to the agreed terms.
This distinction helps businesses avoid treating every outstanding invoice as a collection problem.
Where Are Debtors Shown in Accounts?
Customer receivables are generally presented as assets because they represent amounts the business expects to receive. Depending on the circumstances and accounting framework, trade receivables are commonly treated as current assets when they are expected to be collected within the normal operating cycle or within the relevant short-term period.
However, the reported value of a receivable should reflect its expected recoverability. If there is evidence that a customer may not pay the full amount, the business may need to recognise an appropriate allowance or adjustment under the accounting rules applicable to it.
Debtors Are Different From Cash
This difference is crucial for financial planning.
Suppose a business has £30,000 in outstanding customer invoices and only £8,000 in its bank account. It cannot treat the entire £30,000 as immediately available spending money.
The business must wait for customers to settle their balances. Until then, the receivables may be valuable, but they are not liquid cash.
Why Businesses Need to Monitor Debtors
Debtor management is closely connected to working capital.
If customers pay quickly, a business can recycle its money into stock, wages, suppliers, marketing, equipment, and other expenses. If customers pay slowly, the business may need additional cash to continue normal operations.
Debtors and Cash Flow
A company can report healthy revenue while experiencing cash flow difficulties.
For example, a business might issue £40,000 of invoices during a month but receive only £15,000 from customers. The remaining £25,000 may still be recorded as receivables.
This is why business owners should monitor both sales performance and collection performance.
How to Manage Debtors Properly
Effective debtor management is not simply about chasing late payments. It involves creating a reliable process from the moment a customer is accepted.
Check Customer Payment Terms
Before providing substantial credit, businesses should consider whether the proposed payment terms are suitable. Longer payment periods can increase the amount of money tied up in receivables.
Issue Clear Invoices
Invoices should contain accurate details and clearly explain what the customer is being charged for. Errors can create unnecessary disputes and delays.
Keep Customer Records Updated
Businesses should maintain accurate customer contact information and payment records. This makes it easier to communicate when invoices become due.
Review Outstanding Balances Regularly
A monthly review can identify invoices approaching their due dates as well as older balances that need attention.
A debtor ageing report can be particularly useful because it separates balances according to how long they have remained unpaid.
What Is a Debtor Ageing Report?
A debtor ageing report provides a breakdown of outstanding receivables based on their age.
For example, a business could have:
-
£12,000 not yet due
-
£4,000 overdue by up to 30 days
-
£2,500 overdue by 31 to 60 days
-
£1,500 overdue by more than 60 days
This information provides more insight than simply knowing that total debtors are £20,000.
Older balances generally deserve closer investigation because the longer an invoice remains unpaid, the greater the possibility that collection may become difficult.
Common Challenges With Debtors
Late Payments
Customers may delay payment because of their own cash flow problems, internal approval procedures, or administrative errors.
Invoice Disputes
A customer might challenge an invoice because the agreed price, quantity, delivery, or scope of work differs from what they expected.
Businesses should investigate legitimate disputes rather than treating every delayed payment as deliberate non-payment.
Incorrect Accounting Records
A payment posted against the wrong invoice can leave an account appearing overdue when the customer has actually paid.
Credit notes, refunds, part-payments, and write-offs also need to be recorded correctly.
Unrecoverable Amounts
In some situations, a customer may become unable or unwilling to settle an outstanding balance. Businesses should assess such receivables appropriately under their accounting requirements rather than assuming every invoice will eventually produce cash.
Practical Benefits of Good Debtor Control
A structured approach to debtor management can help businesses:
-
Improve visibility over expected cash receipts
-
Identify overdue invoices sooner
-
Reduce administrative mistakes
-
Spot recurring late-paying customers
-
Support more accurate cash flow planning
-
Maintain reliable financial records
-
Reduce the amount of working capital tied up in receivables
Good debtor management can also improve communication with customers because payment expectations are established clearly from the beginning.
Key Insights for Business Owners
A useful debtor review should consider more than the total outstanding amount.
Business owners should look at the age of each balance, the customer's payment history, the reason for any delay, and the likelihood of receiving the full amount.
For example, £10,000 due from a reliable customer with a five-day delay may represent less immediate concern than £3,000 that has remained unpaid for six months without a clear explanation.
The quality of receivables matters as much as their total value.
Frequently Asked Questions
1. What are debtors in simple terms?
Debtors are individuals or organisations that owe money to a business. In most businesses, they are customers with unpaid invoices for goods or services already supplied.
2. Does a debtor always have an overdue payment?
No. A customer can be a debtor while their invoice is still within the agreed payment period. An account becomes overdue after the payment deadline has passed.
3. Why are debtors important to cash flow?
Debtors represent money that the business expects to receive. Until customers pay, that money cannot be used in the same way as cash already held in the bank.
4. How can a business reduce debtor problems?
Clear payment terms, accurate invoices, regular account reviews, prompt follow-up, and efficient dispute resolution can help reduce unnecessary delays in receiving customer payments.
5. What is the difference between a debtor and a creditor?
A debtor owes money to the business, while a creditor is someone the business owes money to. An unpaid customer invoice creates a debtor balance, while an unpaid supplier invoice creates a creditor balance.
Conclusion
Understanding What Are Debtors provides a clearer view of how credit sales affect business finances. Debtors represent amounts owed to a business, usually by customers who have received goods or services but have not yet made payment.
These balances can be an important part of a company's assets, but they should not be confused with cash. Regular monitoring helps businesses identify overdue invoices, investigate disputes, assess collection risks, and plan their finances more effectively.
Accurate bookkeeping is central to this process. When invoices, payments, credit notes, and adjustments are recorded correctly, business owners can see what customers owe and make better decisions about cash flow and working capital.

 English
 Arabic
 French
 Spanish
 Portuguese
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek